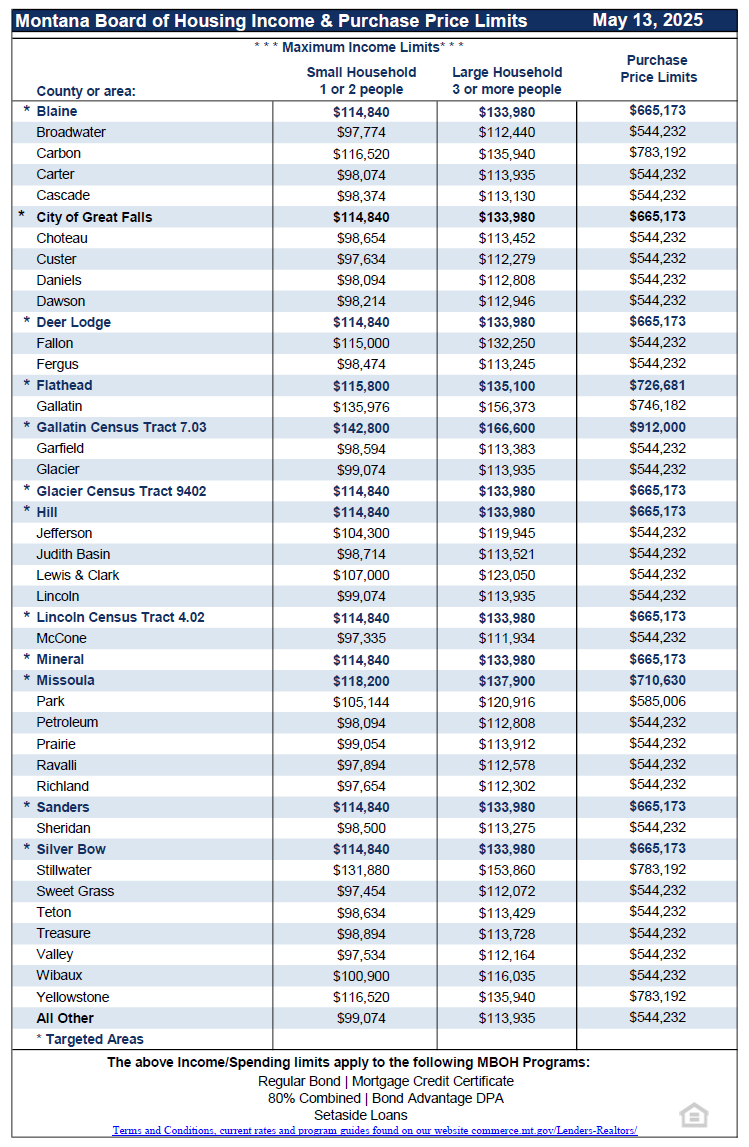
As the Montana housing market continues to navigate a complex economic landscape, the Montana Board of Housing has officially implemented updated fixed interest rates for its suite of homeownership programs. Effective as of late September 2026, these adjustments are designed to provide a more stable and accessible pathway to homeownership for residents across the state. By offering competitive financing options, these programs serve as a critical tool for those looking to secure a foothold in the market despite the persistence of elevated interest rates.
The updated rate structure applies to several key initiatives, most notably the Regular Loan Program and the Veterans Home Loan Program. The Regular Loan Program remains a cornerstone for first-time homebuyers, offering 30-year, low-interest financing for those who meet specific income and purchase price criteria. Meanwhile, the Veterans Home Loan Program continues to provide a significant advantage for those who have served in the armed forces or the Montana National Guard. Under this initiative, eligible veterans can secure a mortgage at a rate 1% lower than the standard Regular Bond Loan Program, providing a meaningful reduction in monthly housing costs.
Navigating Market Challenges
For many Montanans, the current high-rate environment has created significant barriers to entry, particularly as home prices remain elevated in many of the state’s primary hubs. These state-backed programs are specifically engineered to mitigate these pressures. By providing fixed-rate options, the Board of Housing offers borrowers a level of predictability that is often difficult to find in the conventional mortgage market. This stability is essential for long-term financial planning, allowing families to lock in manageable payments rather than contending with the volatility of fluctuating market rates.
Beyond the interest rate adjustments, these programs often work in tandem with other resources, such as down payment assistance, to lower the initial hurdle of homeownership. For prospective buyers, the message is clear: while the broader market may feel restrictive, state-sponsored programs remain a vital resource for those who qualify. Investors and real estate professionals should take note of these changes, as they directly influence the purchasing power of a significant segment of the buyer pool.
As we move into the final quarter of 2026, these updated rates reflect a proactive approach to housing affordability. Whether you are a first-time buyer or a veteran looking to purchase your first home, consulting with a participating lender is the best way to understand how these specific program updates can be leveraged. By staying informed on these developments, Montanans can better position themselves to achieve their homeownership goals in an evolving real estate climate.